


- The Credit Guarantee Fund for Micro Units (CGFMU) was launched in January 2016.
- It supports collateral-free MUDRA loans of up to ₹20 lakh for eligible micro enterprises.
- The scheme is managed by the National Credit Guarantee Trustee Company Limited (NCGTC).
- The annual guarantee fee for non-SHG loans has been reduced to 0.75% from FY 2026-27.
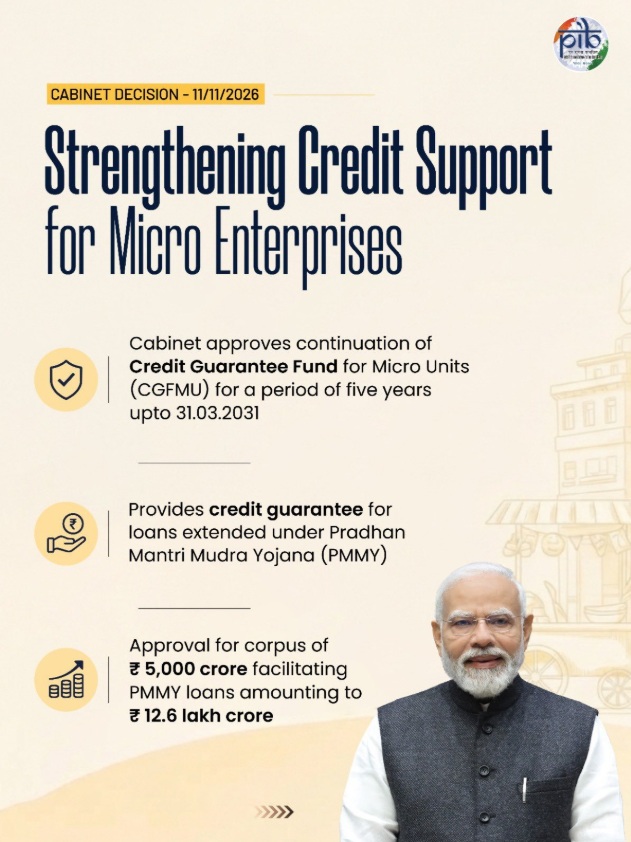
- The Union Cabinet has extended the scheme until 31 March 2031 with an approved corpus of ₹5,000 crore.ay the loan as agreed.
- Department of Financial Services, Ministry of Finance, Government of India
- Phone: 022-69035626 / 022-69035612 (CGFMU Helpdesk)
- Email: [email protected]
- General Contact: 022-69035600
- General Email: [email protected]
Summary of the Scheme | |
|---|---|
| Name of Scheme | Credit Guarantee Fund for Micro Units (CGFMU) |
| Launch Year | 2016 |
| Benefits | Collateral-free MUDRA loans up to ₹20 lakh with credit guarantee support. |
| Beneficiary | Micro enterprises, new entrepreneurs and eligible Self-Help Groups (SHGs). |
| Nodal Agency | National Credit Guarantee Trustee Company Limited (NCGTC) |
| Subscription | Subscribe here to get Update Regarding Scheme |
| Mode of Apply | Online through the JanSamarth Portal or offline through participating banks, NBFCs and MFIs. Borrowers do not apply directly to NCGTC. |
Scheme Introduction: A Brief Overview
Starting or expanding a small business often requires money, but many entrepreneurs find it difficult to arrange collateral or a third-party guarantee for a bank loan. To help such business owners, the Government of India introduced the Credit Guarantee Fund for Micro Units (CGFMU). The scheme encourages banks and other financial institutions to provide collateral-free loans to eligible micro businesses under the Pradhan Mantri MUDRA Yojana (PMMY). Eligible businesses can get MUDRA loans of up to ₹20 lakh under the applicable loan categories.
The CGFMU was launched in January 2016 and is managed by the National Credit Guarantee Trustee Company Limited (NCGTC), a wholly owned company of the Department of Financial Services (DFS), Ministry of Finance, Government of India. NCGTC manages the fund and provides guarantee support to eligible lenders against a specified portion of losses arising from loan defaults. The scheme is administered under the Department of Financial Services.
The main aim of CGFMU is to make business loans more accessible to micro enterprises, especially first-time entrepreneurs and small business owners who may not have assets to offer as security. The government shares a part of the lending risk with financial institutions, encouraging them to provide loans without collateral or third-party guarantees. The guarantee protects the lender, not the borrower. Therefore, CGFMU is not a direct loan, subsidy or loan-waiver scheme.
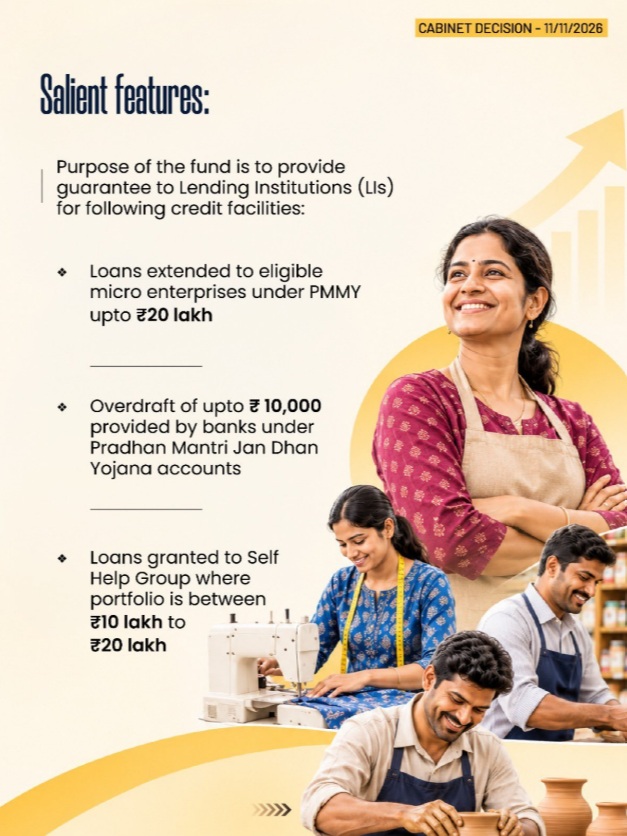
Under PMMY, eligible loans are available in four categories: Shishu (up to ₹50,000), Kishore (above ₹50,000 and up to ₹5 lakh), Tarun (above ₹5 lakh and up to ₹10 lakh) and Tarun Plus (above ₹10 lakh and up to ₹20 lakh). Tarun Plus is available only to borrowers who have previously taken and successfully repaid a Tarun loan. CGFMU also covers eligible PMJDY overdrafts of up to ₹10,000 and qualifying Self-Help Group (SHG) loans above ₹10 lakh and up to ₹20 lakh.
On 11 November 2026, the Union Cabinet approved the continuation of CGFMU for another five years, up to 31 March 2031. The scheme has been approved with a corpus of ₹5,000 crore and is expected to support around ₹12.6 lakh crore in PMMY lending during this period. The Cabinet also reduced the standard annual guarantee fee for non-SHG loans from 1% to 0.75%. The SHG fee remains 0.25% for the first year and 0.50% for subsequent years.
Eligible beneficiaries include new and existing micro businesses involved in manufacturing, trading, services and specified activities allied to agriculture, such as dairy farming, poultry, fisheries, beekeeping and food processing. Eligible Joint Liability Groups (JLGs), Self-Help Groups and certain PMJDY overdraft accounts are also covered. However, pure agricultural loans, such as crop loans and loans for irrigation or land improvement, are not covered. Udyam or MSMED registration is not compulsory specifically for CGFMU guarantee coverage. The lender will still check the business proposal and repayment capacity before approving the loan.
Entrepreneurs do not need to apply separately to NCGTC for the guarantee. They can apply for an eligible MUDRA loan through the JanSamarth Portal or by visiting a participating bank, NBFC or MFI. Applicants generally need to provide the MUDRA loan application form, identity proof, address proof, bank statements and statutory returns, wherever applicable. The lender may ask for additional documents depending on the business and loan requirements. If the loan is approved and meets the scheme conditions, the lender arranges the guarantee cover through NCGTC.
Entrepreneurs exploring other government-backed business financing options can also check related schemes available on GovtSchemes.in. The Pradhan Mantri MUDRA Yojana (PMMY) provides the underlying business loans supported by CGFMU, while the Credit Guarantee Scheme for Startups (CGSS) provides guarantee support for eligible DPIIT-recognised startups seeking debt financing. Similarly, the Credit Guarantee Scheme for Micro and Small Enterprises (CGTMSE) supports eligible micro and small enterprises in accessing institutional credit. Entrepreneurs planning to establish a new micro enterprise can also explore the Prime Minister's Employment Generation Programme (PMEGP), which provides credit-linked subsidy assistance for setting up eligible new enterprises. Each scheme has different eligibility requirements and financial assistance provisions, so applicants should select the option that best matches their business needs.
Scheme Benefits
The Credit Guarantee Fund for Micro Units (CGFMU) makes it easier for eligible micro enterprises to access formal business loans without providing collateral. By sharing the lending risk with financial institutions, the scheme offers several benefits to small business owners and new entrepreneurs.
- Eligible micro enterprises can obtain collateral-free MUDRA loans of up to ₹20 lakh under the applicable loan categories.
- First-time entrepreneurs can access formal business credit to start income-generating activities, even if they have limited credit history.
- Existing small businesses can obtain financial support to meet working capital requirements, purchase equipment and expand their operations.
- Eligible businesses engaged in manufacturing, trading, services and allied agricultural activities can benefit from credit guarantee support.
- Women entrepreneurs can access eligible MUDRA loans and receive support in establishing or expanding their businesses.
- Eligible Self-Help Groups (SHGs) can obtain collateral-free loans ranging from above ₹10 lakh to ₹20 lakh under the scheme.
- Eligible overdrafts of up to ₹10,000 in Pradhan Mantri Jan Dhan Yojana (PMJDY) accounts are also covered.
- The guarantee reduces the risk for participating banks, NBFCs and MFIs, encouraging them to provide formal credit to microbusinesses.
- The standard annual guarantee fee has been reduced from 1% to 0.75% for non-SHG loans from FY 2026-27, as approved by the Union Cabinet.
- The scheme has been extended until 31 March 2031, ensuring continued credit guarantee support for eligible micro enterprises.
Pradhan Mantri MUDRA Yojana Loan Categories Covered Under Credit Guarantee Fund for Micro Units
The Credit Guarantee Fund for Micro Units supports eligible loans sanctioned under the Pradhan Mantri MUDRA Yojana (PMMY). PMMY offers different loan categories based on the amount of credit required by a microbusiness. These categories are Shishu, Kishore, Tarun and Tarun Plus.
The following table explains the loan limits and eligibility conditions under each category:
Loan Category | Loan Amount | Eligibility / Purpose |
|---|---|---|
Shishu | Up to ₹50,000 | For small businesses and entrepreneurs who need initial financial assistance to start or develop a business. |
Kishore | Above ₹50,000 and up to ₹5 lakh | For businesses that have started operations and require additional funds for working capital or business expansion. |
Tarun | Above ₹5 lakh and up to ₹10 lakh | For established microbusinesses that need higher financial assistance to expand or strengthen their operations. |
Tarun Plus | Above ₹10 lakh and up to ₹20 lakh | For entrepreneurs who have previously availed a Tarun-category loan and successfully repaid it. The additional loan is subject to the applicable lending and guarantee conditions. |
All four categories fall under PMMY. However, guarantee coverage under CGFMU is subject to the applicable scheme conditions and the eligibility of the borrower and lending institution. A loan is not automatically covered simply because it falls within one of these categories.
Eligibility Requirements
The Credit Guarantee Fund for Micro Units (CGFMU) supports eligible new and existing micro enterprises that need financial assistance to start or expand their businesses. Applicants must meet the applicable PMMY loan conditions, while the lending institution also checks the business activity and repayment capacity before approving the loan.
The following borrowers and credit facilities are eligible for coverage under the scheme:
- New and existing micro enterprises engaged in eligible manufacturing, trading and service activities can receive credit guarantee support.
- First-time entrepreneurs with a viable business plan for an income-generating activity can apply for an eligible MUDRA loan through a participating lending institution.
- Microbusinesses engaged in retail trade, small manufacturing, food processing, repair services, transport and other eligible business activities can be covered.
- Businesses involved in allied agricultural activities such as dairy farming, poultry, fisheries, beekeeping, livestock rearing, agri-clinics and food processing are eligible.
- Loans of up to ₹10 lakh can be covered under the applicable PMMY categories, subject to the scheme conditions.
- Borrowers applying for loans above ₹10 lakh and up to ₹20 lakh under the Tarun Plus category must have previously availed and successfully repaid a Tarun-category loan.
- Joint Liability Groups (JLGs) operating eligible micro enterprises can also receive guarantee coverage, subject to the applicable loan limits and conditions.
- Eligible Self-Help Groups (SHGs) with loans above ₹10 lakh and up to ₹20 lakh can receive coverage under the scheme.
- Eligible overdraft facilities of up to ₹10,000 provided through Pradhan Mantri Jan Dhan Yojana (PMJDY) accounts are also covered.
- Applicants must approach a participating bank, NBFC, MFI or other eligible lending institution registered with NCGTC.
- Udyam or MSMED registration is not compulsory specifically for obtaining CGFMU guarantee coverage.
- The loan must satisfy the applicable scheme conditions, including the collateral-free lending requirement. The lender must assess the applicant's business proposal and repayment capacity.
Activities not covered: Purely agricultural loans, including crop loans and loans for land improvement, irrigation canals and wells, are not eligible for CGFMU coverage. Loans already covered by another government guarantee or guarantor, and accounts classified as NPA when seeking fresh guarantee coverage, are also excluded under the applicable scheme rules.
Required Documents
To apply for a MUDRA loan covered under the Credit Guarantee Fund for Micro Units (CGFMU), applicants need to submit a few basic documents to the participating bank or lending institution. The exact documents may vary depending on the loan category, business requirements and lender's verification process. The following documents are generally required:
- Completed MUDRA loan application form.
- Identity proof of the applicant, such as Aadhaar Card, Voter ID Card, Driving Licence or Passport.
- Address proof of the applicant, such as an Aadhaar Card, Voter ID Card, Passport or recent utility bill.
- Recent bank statements, if applicable, to help the lender assess the applicant's financial position.
- Statutory returns, wherever applicable.
- Any additional documents requested by the bank or lending institution during the loan assessment process.
Steps to Apply
Entrepreneurs who want to benefit from the Credit Guarantee Fund for Micro Units (CGFMU) do not need to submit a separate application for the guarantee. They must first apply for an eligible MUDRA loan through a participating bank, NBFC or MFI. The lender evaluates the application and obtains the CGFMU guarantee cover from NCGTC if the loan meets the scheme conditions. Applicants can follow either the online or offline application process explained below.
Method 1: Apply Online Through the JanSamarth Portal
- Open the JanSamarth Portal and find the Business Activity Loan section on the homepage.
- Click on the "Check Eligibility" option to begin checking your eligibility for a business loan.
- Select the Pradhan Mantri MUDRA Yojana (PMMY) or the relevant business loan option and provide the required details about your business.
- Enter information about your business activity, whether it is new or existing, estimated project cost and the loan amount you need.
- Submit the required information to check the loan schemes and options for which you may qualify.
- If eligible, proceed with the application by selecting the available loan option and following the portal's login or registration instructions.
- Register using your active mobile number and complete the OTP verification. An email address may also be registered if required.
- Fill in the loan application form, upload the requested documents and select a participating lending institution, where the option is available.
- Submit the application and save the application reference number to check its progress later.
- Log in to the portal to track your application status and respond to any additional information or document requests from the lender.
Method 2: Apply Offline Through a Bank or Lending Institution
- Visit a nearby participating bank, Regional Rural Bank, Small Finance Bank, cooperative bank, NBFC or Microfinance Institution that provides MUDRA loans.
- Ask the bank representative for the MUDRA loan application form under the appropriate category, such as Shishu, Kishore, Tarun or Tarun Plus.
- Fill in the application form with your personal details, business information, loan requirement and other necessary particulars.
- Attach the required documents, including identity proof, address proof, bank statements and statutory returns, wherever applicable.
- Submit the completed application and supporting documents to the lending institution for verification.
- The lender will assess your business proposal, repayment capacity and eligibility before deciding whether to approve the loan.
- If the loan is sanctioned and meets CGFMU conditions, the lending institution will arrange the applicable guarantee coverage through NCGTC. You do not need to apply separately for this guarantee.
Important: CGFMU does not provide automatic loan approval. The final decision rests with the lending institution after evaluating the applicant's eligibility and repayment capacity. The guarantee fee is paid by the lender to NCGTC, although the lender may pass this cost on to the borrower as permitted under the scheme. Applicants should obtain loan information directly from participating financial institutions and avoid paying unauthorised agents who promise guaranteed loan approval.
Guarantee Coverage and Claim Settlement Process
Under the Credit Guarantee Fund for Micro Units (CGFMU), NCGTC provides guarantee support to eligible lending institutions against a specified portion of the credit risk arising from covered loans. The Union Cabinet approved the continuation of the scheme for five years, covering FY 2026-27 to FY 2030-31, with a corpus of ₹5,000 crore on 11 November 2026. The revised framework includes the following provisions:
Particulars | Revised Provisions |
|---|---|
Scheme Continuation | Extended for five years, up to 31 March 2031 (FY 2026-27 to FY 2030-31). |
Approved Corpus | ₹5,000 crore. |
Working Capital Facilities | Guarantee coverage will be linked to the disbursement amount. |
Term Loans | Guarantee coverage will be linked to the outstanding loan amount. |
Non-SHG Loans | Standard annual guarantee fee reduced from 1% to 0.75%. |
SHG Loans | Guarantee fee remains 0.25% for the first year and 0.50% for subsequent years. |
PMMY Loans | Eligible loans up to ₹20 lakh. |
PMJDY Overdrafts | Eligible overdrafts up to ₹10,000. |
SHG Loan Portfolios | Eligible loan portfolios above ₹10 lakh and up to ₹20 lakh. |
Claim Settlement Process
Step | Process |
|---|---|
1. Loan Default | If a borrower defaults on an eligible loan, the lending institution follows the applicable recovery procedures. |
2. Claim Submission | The lending institution submits a guarantee claim to NCGTC after fulfilling the applicable claim conditions. |
3. Claim Verification | NCGTC examines the claim and verifies whether it meets the scheme's requirements. |
4. Guarantee Payment | NCGTC releases the admissible guarantee amount to the lending institution according to the applicable guidelines. |
5. Recovery Sharing | If the lender subsequently recovers money from the borrower, the recovered amount is shared between the lender and the guarantee fund in the prescribed proportion. |
Important: CGFMU protects the lending institution against eligible credit losses; it does not waive the borrower's loan liability. Borrowers remain responsible for repaying the outstanding loan, even if the lender receives payment under the guarantee.
Relevant Links
- Department of Financial Services, Ministry of Finance
- Credit Guarantee Fund for Micro Units (CGFMU) – Official Scheme Portal
- Credit Guarantee Fund for Micro Units Guidelines and Frequently Asked Questions (PDF)
- CGFMU Gazette Notification – October 2024
- Latest Cabinet Approval – CGFMU Extension up to 2031
- JanSamarth Loan Application Portal
- MUDRA Official Website
- NCGTC Contact and Grievance Information
Contact Information
National Credit Guarantee Trustee Company Limited (NCGTC) Department of Financial Services, Ministry of Finance, Government of India
- Phone: 022-69035626 / 022-69035612 (CGFMU Helpdesk)
- Email: [email protected]
- General Contact: 022-69035600
- General Email: [email protected]
- Grievance Email: [email protected]
- Address: National Credit Guarantee Trustee Company Limited (NCGTC), 1410, 14th Floor, Parinee Crescenzo, Plot No. C-38 & C-39, G-Block, Bandra Kurla Complex (BKC), Bandra East, Mumbai, Maharashtra – 400051.
For questions related to MUDRA loan applications, applicants should first contact the bank, NBFC or MFI through which they have applied. For CGFMU guarantee-related queries, they can contact the NCGTC helpdesk using the details provided above.
Frequently Asked Questions
The Credit Guarantee Fund for Micro Units (CGFMU) is a Government of India scheme that encourages banks and other financial institutions to provide collateral-free loans to eligible micro enterprises under PMMY.
The CGFMU scheme was launched in January 2016 to improve access to formal credit for micro businesses and small entrepreneurs.
The National Credit Guarantee Trustee Company Limited (NCGTC), a wholly owned company of the Department of Financial Services, Ministry of Finance, manages the fund as its trustee.
Eligible micro enterprises can obtain MUDRA loans of up to ₹20 lakh under the applicable PMMY categories, subject to the scheme conditions.
Eligible new and existing micro enterprises engaged in manufacturing, trading, services and specified allied agricultural activities can receive guarantee coverage. Certain SHG, JLG and PMJDY overdraft facilities are also covered.
No. Udyam or MSMED registration is not compulsory specifically for obtaining CGFMU guarantee coverage. However, applicants must meet the applicable loan and scheme conditions.
No. Borrowers must apply for an eligible MUDRA loan through a participating bank, NBFC or MFI. The lending institution completes the guarantee-related formalities with NCGTC.
From FY 2026-27, the standard annual guarantee fee for non-SHG loans is 0.75%. For eligible SHG loans, the fee is 0.25% for the first year and 0.50% for subsequent years.
No. CGFMU is a credit guarantee scheme that protects eligible lenders against a specified portion of credit losses. Borrowers remain responsible for repaying their loans.
The Union Cabinet approved the continuation of CGFMU for five years, covering FY 2026-27 to FY 2030-31, up to 31 March 2031.
Do you have any question regarding schemes, submit it in scheme forum and get answers:
Feel free to click on the link and join the discussion!
This forum is a great place to:
- Ask questions: If you have any questions or need clarification on any aspect of the topic.
- Share your insights: Contribute your own knowledge and experiences.
- Connect with others: Engage with the community and learn from others.
I encourage you to actively participate in the forum and make the most of this valuable resource.


Add new comment