


- MCGS-MSME was launched on 17 February 2025 to improve access to finance for eligible MSMEs.
- Eligible businesses can obtain term loans of up to ₹100 crore with 60% guarantee coverage.
- Exporter MSMEs can access loans of up to ₹20 crore with 75% guarantee coverage.
- Manufacturing and service-sector MSMEs are eligible under the revised guidelines.
- Department of Financial Services, Ministry of Finance, Government of India
- Scheme-specific Phone: 022-69035634 / 022-69035625 / 022-69035611
- Scheme-specific Email: [email protected]
- General Phone: 022-69035600
Summary of the Scheme | |
|---|---|
| Name of Scheme | Mutual Credit Guarantee Scheme for MSMEs (MCGS-MSME) |
| Launch Year | 2025 |
| Benefits | Credit guarantee coverage of 60% of the amount in default, with loans up to ₹100 crore. |
| Beneficiary | Eligible manufacturing and service-sector MSMEs, including qualifying exporter MSMEs. |
| Nodal Agency | National Credit Guarantee Trustee Company Limited (NCGTC) |
| Subscription | Subscribe here to get Update Regarding Scheme |
| Mode of Apply | Through eligible Member Lending Institutions (MLIs), such as participating banks and financial institutions. |
Scheme Introduction: A Brief Overview
Purchasing modern machinery, upgrading equipment or expanding production capacity often requires a significant investment, which can be difficult for many small businesses to arrange. To address this challenge, the Government of India introduced the Mutual Credit Guarantee Scheme for MSMEs (MCGS-MSME). The scheme helps eligible Micro, Small and Medium Enterprises (MSMEs) obtain term loans of up to ₹100 crore for purchasing plant, machinery and equipment. It provides 60% guarantee coverage to participating lenders against the eligible amount in default. A special facility is also available for qualifying exporter MSMEs, offering loans of up to ₹20 crore with 75% guarantee coverage.
The scheme was approved on 29 January 2025 and formally launched on 17 February 2025 by the Union Finance Minister. It is designed to improve access to institutional finance, encourage investment in business infrastructure, strengthen domestic manufacturing and support the growth of the MSME sector. Following the revision announced in March 2026, eligible service-sector enterprises were also included, and the minimum share of plant, machinery and equipment in the project cost was reduced from 75% to 60%.
The Department of Financial Services (DFS), Ministry of Finance, established the Mutual Credit Guarantee Fund for MSMEs (MCGF-MSME), which is managed by the National Credit Guarantee Trustee Company Limited (NCGTC). NCGTC provides the guarantee support to eligible Member Lending Institutions (MLIs), including Scheduled Commercial Banks, All India Financial Institutions and qualifying NBFCs. These lenders assess MSME loan applications, sanction eligible term loans and complete the guarantee-related formalities with NCGTC.
One of the major benefits of MCGS-MSME is that eligible businesses can access substantial term loan assistance without bearing the entire lending risk themselves from the lender's perspective. Under the general facility, the maximum loan amount covered by the guarantee is ₹100 crore, with 60% guarantee coverage. Eligible exporters can receive up to ₹20 crore with 75% coverage. The scheme also provides for a refundable upfront contribution, subject to satisfactory loan performance and the applicable conditions. These provisions can help businesses invest in machinery, modernise operations, improve production capacity and expand their activities.
To qualify, an MSME must have a valid Udyam Registration Number and should not be classified as a Non-Performing Asset (NPA) with any lender. The proposed project must involve the purchase of eligible plant, machinery or equipment, which should account for at least 60% of the total project cost. Both manufacturing and service-sector enterprises can be considered under the revised scheme. A separate facility is available for eligible profitable exporters that meet the prescribed export turnover and export-realisation conditions.
MSMEs cannot apply directly to NCGTC for guarantee coverage. Businesses interested in the scheme must approach a participating bank or financial institution with their loan proposal, Udyam Registration details, project report and other required documents. The lender evaluates the business and its repayment capacity before deciding whether to sanction the term loan. If the loan meets the scheme conditions, the lender applies to NCGTC for the applicable guarantee cover. The borrower must repay the loan according to the agreed repayment schedule.
MSMEs exploring other government-backed financing options can also read about the Credit Guarantee Scheme for Micro and Small Enterprises (CGTMSE), which helps eligible micro and small businesses access institutional credit through guarantee support. Businesses looking for funds against unpaid invoices can explore the Credit Guarantee Fund Scheme for Factoring. Similarly, microbusiness owners seeking loans under the Pradhan Mantri MUDRA Yojana can learn about the Credit Guarantee Fund for Micro Units (CGFMU). Each scheme serves different financing needs and has its own eligibility conditions.
Scheme Benefits
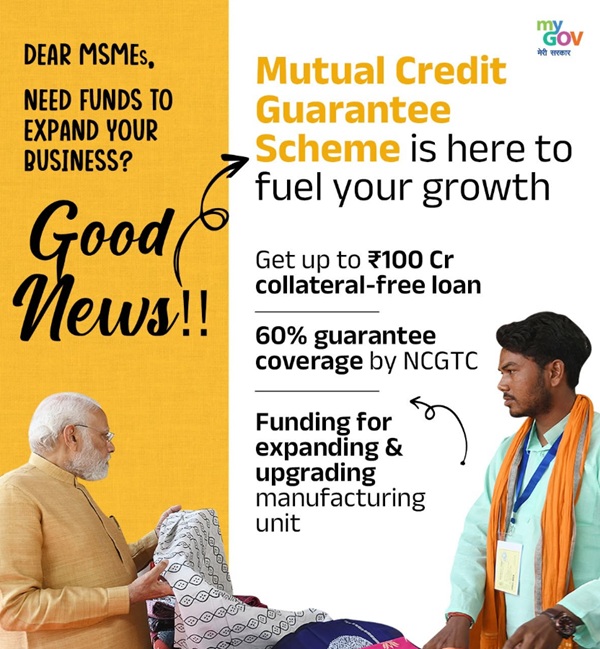
The Mutual Credit Guarantee Scheme for MSMEs (MCGS-MSME) helps eligible businesses arrange finance for purchasing machinery, upgrading equipment and expanding their operations. Some of its key benefits are as follows:
- Eligible MSMEs can get term loans of up to ₹100 crore to purchase plant, machinery and equipment for their businesses.
- The scheme provides 60% guarantee coverage to participating lenders against the eligible loan default, helping businesses access institutional finance more easily.
- Eligible exporter MSMEs can obtain loans of up to ₹20 crore with 75% guarantee coverage.
- Both manufacturing and service-sector MSMEs are covered under the revised scheme.
- The machinery and equipment investment requirement has been reduced from 75% to 60% of the total project cost, allowing more businesses to qualify.
- Under the general facility, businesses must make an upfront contribution of 5% of the loan amount, up to a maximum of ₹5 crore. This contribution can be refunded in instalments from the fourth year onwards, subject to satisfactory loan performance.
- Eligible exporters need to contribute 2% of the loan amount, up to a maximum of ₹40 lakh. This amount is refundable in two instalments during the fourth and fifth years, subject to scheme conditions.
- For loans of up to ₹50 crore, the repayment period can be up to eight years, with a principal repayment break of up to two years.
- The scheme helps businesses purchase modern machinery, upgrade equipment and improve their production capacity.
- By making loans more accessible for eligible business investments, the scheme supports MSME expansion and improves their competitiveness.
Note: MCGS-MSME provides a guarantee to the lending institution, not a direct subsidy or loan waiver to the borrower. The MSME remains responsible for repaying the loan as agreed with the lender.
Loan Amount and Guarantee Coverage Under MCGS-MSME
One of the main advantages of the Mutual Credit Guarantee Scheme for MSMEs is that it helps eligible businesses obtain larger term loans for purchasing machinery, equipment and other assets required for business expansion. The loan limit and guarantee coverage depend on whether the applicant comes under the general MSME facility or the special exporter facility.
Particulars | General MSME Facility | Exporter Facility |
|---|---|---|
Maximum Loan Amount | Up to ₹100 crore | Up to ₹20 crore |
Guarantee Coverage | 60% of the amount in default | 75% of the amount in default |
Minimum Machinery and Equipment Share | 60% of total project cost | 60% of total project cost |
For example, suppose a bank sanctions a term loan of ₹1 crore to an eligible MSME. If the eligible amount in default is ₹40 lakh, the guarantee coverage under the general facility would be 60% of ₹40 lakh, which comes to ₹24 lakh. The remaining amount is not automatically waived, and the borrower remains responsible for repaying the loan.
It is important to understand that the guarantee protects the participating lender against a specified portion of the eligible default. It is not a subsidy or discount on the loan amount received by the MSME.
Eligibility Requirements
To receive financial assistance under the Mutual Credit Guarantee Scheme for MSMEs (MCGS-MSME), businesses must meet certain conditions related to their registration, loan purpose and financial status. The main eligibility requirements are as follows:
- The applicant must be a Micro, Small or Medium Enterprise (MSME) engaged in manufacturing or service activities.
- The business must have a valid Udyam Registration Number at the time of loan sanction.
- The applicant's loan account must not be classified as a Non-Performing Asset (NPA) with any lender.
- The loan must be used to purchase eligible plant, machinery or equipment for the business.
- The cost of plant, machinery and equipment must account for at least 60% of the total project cost.
- Both existing businesses and new projects can be considered, provided they meet the scheme conditions.
- For the special exporter facility, the business must be profitable and must have exported at least 25% of its sales turnover in each of the previous three financial years.
- Exporters must also ensure that the write-off of export proceeds is less than 10% of their export turnover in each of the previous three financial years.
- The loan must be obtained through an eligible Member Lending Institution (MLI), such as a Scheduled Commercial Bank, All India Financial Institution or qualifying NBFC registered with NCGTC.
- The lending institution must complete the prescribed registration, documentation and guarantee-related formalities with NCGTC.
Upfront Contribution and Guarantee Fee
Businesses receiving loans under MCGS-MSME must meet the prescribed upfront contribution requirements. The contribution and annual guarantee fee differ between the general MSME facility and the special exporter facility.
Particulars | General MSME Facility | Exporter Facility |
|---|---|---|
Upfront Contribution | 5% of the loan amount, maximum ₹5 crore | 2% of the loan amount, maximum ₹40 lakh |
Contribution Refund | 1% each year from the fourth year onwards | 1% in the fourth year and 1% in the fifth year |
Guarantee Fee in Sanction Year | Nil | Nil |
Annual Guarantee Fee Thereafter | 1.5% per year for the next three years and 1% per year thereafter | 0.50% per year thereafter |
The upfront contribution is refundable according to the prescribed schedule, subject to satisfactory loan account performance and the applicable scheme conditions. The annual guarantee fee is charged separately from the upfront contribution.
MSMEs should also remember that the guarantee-related contribution and fees are governed by the scheme guidelines. They should confirm the applicable amount and payment arrangements with their participating lending institution before taking the loan.
Required Documents
Businesses applying for a term loan under the Mutual Credit Guarantee Scheme for MSMEs (MCGS-MSME) need to provide documents to verify their registration, financial position and proposed investment in machinery or equipment. The exact requirements may vary depending on the lending institution and the nature of the project. Generally, applicants may be asked to submit the following documents:
- Udyam Registration Certificate of the MSME.
- PAN card and identity and address proof of the proprietor, partners or authorised directors.
- Business registration documents, such as a partnership deed, LLP agreement or Certificate of Incorporation, wherever applicable.
- GST registration certificate and GST returns, if applicable.
- Project report explaining the business, proposed investment and purpose of the loan.
- Quotations or pro forma invoices for the plant, machinery or equipment to be purchased.
- Details of the total project cost, including the amount allocated to machinery and equipment.
- Previous years' financial statements, including balance sheets and profit and loss statements, if available or required by the lender.
- Income Tax Returns (ITRs) and recent bank account statements of the business.
- Details of existing loans and their repayment status.
- Property or collateral-related documents, if security is offered or requested by the lender.
- For exporter applicants, export turnover details and documents showing export proceeds realised during the previous three financial years.
- Any additional documents or declarations requested by the participating bank or financial institution.
Applicants should check the document checklist of their chosen lending institution before submitting the application, as the final requirements depend on the lender's assessment and the applicable scheme guidelines.
Steps to Apply
Getting financial assistance under the Mutual Credit Guarantee Scheme for MSMEs (MCGS-MSME) starts with choosing a participating bank or financial institution. MSMEs do not need to apply separately to NCGTC for the guarantee, as the lending institution completes this process after approving the loan. Here is how businesses can proceed:
- First, check that your business has a valid Udyam Registration Number and meets the scheme's eligibility conditions.
- Prepare a project report explaining the machinery or equipment you want to purchase, the total project cost and the amount of loan required.
- Approach a participating bank, All India Financial Institution or eligible NBFC that is registered as a Member Lending Institution (MLI) under the scheme.
- Ask the lender whether your proposed term loan can be covered under MCGS-MSME. You can also check the participating institutions through the NCGTC scheme page.
- Submit the loan application along with your Udyam Registration Certificate, business details, financial documents, machinery quotations and other papers requested by the lender.
- The bank or financial institution will examine your project, repayment capacity and eligibility before deciding whether to sanction the loan.
- After sanctioning the eligible loan, the lender uploads the loan details to the NCGTC portal using its registered login credentials and completes the prescribed guarantee formalities.
- The lender pays the applicable upfront contribution and guarantee fees to obtain the guarantee cover from NCGTC.
- Once the guarantee formalities are completed, the loan is disbursed according to the terms agreed between the MSME and the lending institution.
MSMEs should remember that the online guarantee application is submitted by the participating lender, not by the borrower. Therefore, businesses should contact their chosen bank or financial institution for loan application forms, document requirements and application status.
Important Conditions of MCGS-MSME
Before applying for a loan under MCGS-MSME, businesses should understand a few important conditions. These rules help ensure that the loan is used for the approved purpose and that the guarantee remains valid throughout the applicable period.
- The loan must be used for purchasing eligible plant, machinery and equipment. It cannot be treated as a general-purpose loan for unrelated business expenses.
- The cost of plant, machinery and equipment must account for at least 60% of the total project cost.
- The borrower must have a valid Udyam Registration Number and should not be classified as an NPA with any lender when applying under the scheme.
- The guarantee cover has a two-year lock-in period from the date it becomes effective. The lender cannot invoke the guarantee during this period.
- If the loan account becomes an NPA, the lending institution must report the relevant details to NCGTC within the prescribed period, including the applicable 180-day reporting requirement.
- The lender must initiate the required legal recovery proceedings and fulfil the other claim conditions before invoking the guarantee.
- After an eligible claim is accepted, 75% of the admissible claim amount is paid initially. The remaining 25% is released after the prescribed recovery proceedings are completed or the applicable limitation period expires, subject to the guidelines.
- The guarantee protects the lender against the eligible portion of the default. It does not release the MSME from its responsibility to repay the loan.
- The general facility provides guarantee coverage for up to 10 years, subject to the scheme guidelines.
- The scheme is available for four years from 24 February 2026, the date of the revised operational guidelines, or until cumulative guarantees of ₹7 lakh crore are issued, whichever occurs earlier.
Businesses should carefully review the applicable conditions with their lending institution before accepting the loan. The guarantee, claim and repayment provisions are subject to the latest operational guidelines issued by NCGTC.
Difference Between MCGS-MSME and CGTMSE
Both the Mutual Credit Guarantee Scheme for MSMEs (MCGS-MSME) and the Credit Guarantee Scheme for Micro and Small Enterprises (CGTMSE) help businesses access institutional finance through credit guarantee support. However, their purpose, eligible borrowers and loan requirements are different.
Basis | MCGS-MSME | CGTMSE |
|---|---|---|
Main Purpose | Supports term loans for purchasing plant, machinery and equipment. | Supports eligible credit facilities for micro and small enterprises. |
Eligible Businesses | Eligible manufacturing and service-sector MSMEs, including qualifying exporters. | Eligible micro and small enterprises. |
Loan Type | Term loans for eligible capital expenditure. | Eligible term loans and working capital facilities. |
Maximum Loan Limit | Up to ₹100 crore under the general facility and ₹20 crore under the exporter facility. | Up to ₹10 crore under the applicable CGTMSE coverage framework. |
Guarantee Coverage | 60% for the general facility and 75% for eligible exporters. | Varies according to the borrower's category, loan amount and applicable scheme provisions. |
Implementing Agency | National Credit Guarantee Trustee Company Limited (NCGTC). | Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE). |
In simple terms, MCGS-MSME is particularly relevant for eligible businesses planning to invest in machinery, equipment or production facilities. CGTMSE may be more suitable for eligible micro and small businesses seeking other types of credit facilities, including working capital finance. Applicants should compare the eligibility conditions and lending requirements before choosing a financing route.
Relevant Links
- Department of Financial Services (DFS), Ministry of Finance
- MCGS-MSME Official Scheme Portal – NCGTC
- Revised Operational Guidelines of Mutual Credit Guarantee Scheme for MSMEs
- Government Announcement on Mutual Credit Guarantee Scheme for MSMEs- Modifications
- Udyam Registration Portal
Contact Information
For queries related to the Mutual Credit Guarantee Scheme for MSMEs (MCGS-MSME), applicants can contact the National Credit Guarantee Trustee Company Limited (NCGTC), which manages the scheme on behalf of the Department of Financial Services, Ministry of Finance.
Department of Financial Services, Ministry of Finance, Government of India
{(Implementing Agency: National Credit Guarantee Trustee Company Limited (NCGTC)}
- Scheme-specific Phone: 022-69035634 / 022-69035625 / 022-69035611
- Scheme-specific Email: [email protected]
- General Phone: 022-69035600
- General Email:[email protected]
- Address: National Credit Guarantee Trustee Company Limited (NCGTC), 1410, 14th Floor, Parinee Crescenzo, Plot No. C-38 & C-39, G-Block, Bandra Kurla Complex (BKC), Bandra East, Mumbai, Maharashtra – 400051.
- Official Contact Page: NCGTC Contact Us
For questions about a loan application, sanction or disbursement, MSMEs should also contact the bank or financial institution through which they have applied. The lender handles the borrower's loan application and submits the guarantee request to NCGTC.
Frequently Asked Questions
MCGS-MSME is a Government of India scheme that helps eligible MSMEs obtain term loans for purchasing plant, machinery and equipment. It provides credit guarantee coverage to participating banks and financial institutions to encourage lending to MSMEs.
The scheme was approved on 29 January 2025 and formally launched on 17 February 2025 by the Union Finance Minister.
Eligible MSMEs can obtain term loans of up to ₹100 crore under the general facility. Eligible exporter MSMEs can access loans of up to ₹20 crore under the special exporter facility.
The scheme provides 60% guarantee coverage against the eligible amount in default under the general facility. Eligible exporters can receive 75% guarantee coverage.
Yes. Following the March 2026 revision, eligible service-sector MSMEs can also apply under the scheme, along with manufacturing enterprises.
Plant, machinery and equipment must account for at least 60% of the total project cost. This requirement was reduced from the earlier 75% under the revised guidelines.
Yes. Under the general facility, the 5% upfront contribution is refundable at 1% per year from the fourth year onwards, subject to satisfactory loan performance. For eligible exporters, the 2% contribution is refundable in two instalments during the fourth and fifth years.
For general facility loans of up to ₹50 crore, the repayment period can be up to eight years, with a principal moratorium of up to two years. Eligible exporter loans also have a repayment period of up to eight years with a principal moratorium of up to two years.
No. MSMEs must approach a participating bank or financial institution for a loan. The lending institution completes the guarantee application process with the National Credit Guarantee Trustee Company Limited (NCGTC).
The scheme should not be treated as an unconditional collateral-free loan facility. The participating lender assesses the borrower's creditworthiness and security arrangements according to the applicable scheme guidelines.
No. The scheme primarily supports term loans for purchasing eligible plant, machinery and equipment. It is not a general working capital loan facility.
The general MSME facility provides guarantee coverage for up to 10 years, subject to the scheme conditions and applicable guidelines.
Do you have any question regarding schemes, submit it in scheme forum and get answers:
Feel free to click on the link and join the discussion!
This forum is a great place to:
- Ask questions: If you have any questions or need clarification on any aspect of the topic.
- Share your insights: Contribute your own knowledge and experiences.
- Connect with others: Engage with the community and learn from others.
I encourage you to actively participate in the forum and make the most of this valuable resource.


వ్యాఖ్యానించండి